You don't need a fat savings account to drive off the lot. From lease-to-own programs to employer perks you've never heard of, there are legitimate strategies that put you behind the wheel without breaking the bank—or maxing out your credit card.
#1: Lease-to-Own Programs
Lease-to-own car programs let you drive now and build equity toward ownership. You make monthly payments, and a portion goes toward the eventual purchase price. This option works well if you're unsure about long-term commitment or have shaky credit. For example, some dealerships partner with financing companies to offer zero-down lease-to-own deals on used vehicles, letting you test-drive before you buy.
#2: Employer Car Benefits

Many corporations offer car allowances, stipends, or subsidized leasing as part of employee compensation packages. Tech companies, consulting firms, and corporate chains often include this in benefits. You might not realize it's an option until you ask HR. If your employer offers one, you could essentially get a car funded through payroll deductions without an upfront payment.
#3: Family Loans or Gifts

Borrowing from family members or receiving a car as a gift remains one of the fastest routes to ownership. Unlike traditional lenders, family might offer zero interest, flexible repayment, or no repayment at all. Set clear terms in writing to avoid misunderstandings. A relative who's buying a new car might be thrilled to pass their current vehicle to you interest-free.
Advertisement
#4: Buy Here, Pay Here Dealerships
These specialized dealerships sell used cars directly and finance them in-house without requiring a down payment. You make weekly or monthly payments to the lot itself, not a bank. The tradeoff: higher interest rates and prices than traditional financing. However, they typically accept buyers with poor credit or no credit history, and you drive away same-day.
#5: Credit Union Auto Loans

Credit unions often offer lower interest rates and more flexible lending standards than banks, sometimes with zero-down options for members in good standing. If you're part of a credit union, ask about their auto lending programs. Many unions have partnerships or specific products designed for first-time buyers. Your membership history and savings account balance can offset the lack of a down payment.
#6: Manufacturer Rebate Programs
Car manufacturers occasionally run incentive programs offering cash rebates, low-interest financing, or deferred payment options. These promotions are often tied to specific models or seasons when dealerships need to move inventory. Rather than pocketing a rebate yourself, ask the dealer to apply it directly to eliminate or reduce your down payment requirement.
Advertisement
#7: Non-Profit Car Donation Programs

Some non-profits donate or heavily subsidize vehicles for low-income individuals, single parents, or people entering the workforce. Organizations like Cars for Change or local community action agencies maintain waiting lists. Eligibility criteria vary, but many require proof of income and a job offer. You might receive a car with minimal or no money required, though insurance remains your responsibility.
#8: Peer-to-Peer Car Lending

Online platforms connect individual car lenders with borrowers, often with more lenient terms than banks. You can borrow directly from people rather than institutions. Some P2P lenders specialize in zero-down auto purchases or allow collateral-based lending. Research platforms carefully and ensure you understand the terms, interest rate, and insurance requirements before committing.
#9: Government Assistance Programs

Federal and state governments offer car ownership assistance in select regions, targeting low-income families, veterans, or workers transitioning to new jobs. The USDA has rural transportation programs; some states offer tax credits or grants. Contact your state's workforce development office or department of transportation to explore local options specific to your situation.
Advertisement
#10: Side Hustle to Bridge the Gap

Instead of waiting for a down payment, use a quick side gig to fund it. Gig work like food delivery, rideshare, or freelancing can generate cash rapidly. Some people work intensively for three to six months to accumulate enough capital for a minimal down payment or to qualify for better lending terms. This approach also strengthens your credit profile by showing recent income activity.
#11: Assuming Existing Car Loans

If someone else owns a vehicle they can no longer afford, you may assume their car loan with lender approval. This transfers ownership and payment responsibility to you—no down payment needed. The existing loan balance becomes your obligation. Verify the vehicle's condition and confirm the lender permits loan assumption before proceeding.
#12: Trade-In Credits Without Down Payment
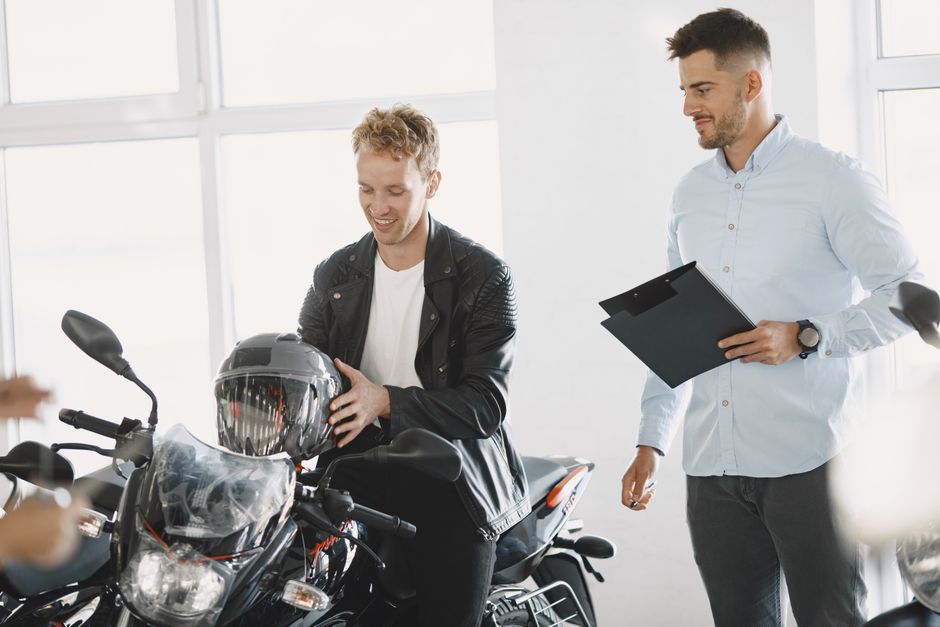
If you own anything of value—a motorcycle, ATV, boat, or collectible—you can trade it in toward a car purchase and ask the dealer to waive the down payment using that credit. The trade-in value offsets the down payment requirement entirely. This works especially well at dealerships with diverse inventory who can resell your item separately.
Advertisement
#13: Rent-to-Own Auto Programs

Companies like Carvana, Vroom, and local rent-to-own shops offer structured programs where your rental payments accumulate credit toward purchase. After a set period (typically 12–36 months), you own the vehicle outright. No down payment is required upfront, though monthly payments are higher than traditional financing to account for the ownership path.
#14: Co-Signer Financing

A co-signer with stronger credit can help you secure a zero-down auto loan by backing your obligation. Lenders view co-signers as guarantors and may waive the down payment if the co-signer's creditworthiness is solid. Family members or close friends often serve this role. Both parties must understand that the co-signer is legally responsible if you default.
#15: Inheritance or Estate Settlement
If a family member passes away and leaves you a vehicle in their will or estate, you inherit it free and clear. Even if the estate has a small loan, executors often use estate funds to pay it off. This is not an action you can take immediately, but it's a legitimate zero-down pathway that countless people use. Estate settlement timelines vary by state and complexity.
Getting a car with no money down is achievable—it just requires knowing where to look and what programs exist. Explore the option that aligns best with your financial situation, credit profile, and timeline.
Advertisement